You’ve spent decades adapting your accounting practice. AI now asks for another substantial investment of your time, attention and energy. Before committing your next five years, it is worth asking: do you actually want to do the next lap?
If, like me, you started in accounting when handwritten cashbooks, ten-column worksheets and T-accounts were part of the working day, you have already travelled a considerable distance. Red, green and black pens each had their purpose. Finding an error could become an afternoon’s entertainment.
Since then, you’ve adapted to computers, cloud accounting, changing regulations and rising client expectations—all while keeping the practice running.
You may still enjoy the clients, the work and the professional relationships you have built. The question is whether you also want the job of leading the firm through its next transformation.
We have been adapting for 40 years
My generation of accountants has hardly been resistant to change.
We went from handwritten ledgers to desktop computers.
Then came accounting software, spreadsheets, email, the internet, cloud accounting, portals, digital signatures, automation and an ever-expanding technology stack.
At the same time, the regulatory environment became progressively more complicated.
Tax legislation grew. Professional standards evolved. Privacy and cyber security became management issues. Client expectations changed. Finding and retaining good people became harder.
And now Australian accountants providing designated services have entered the expanded AML/CTF regime, bringing requirements around risk assessment, customer due diligence, reporting, record keeping and compliance programs.
Most accountants have simply kept adapting.
That is what professionals do.
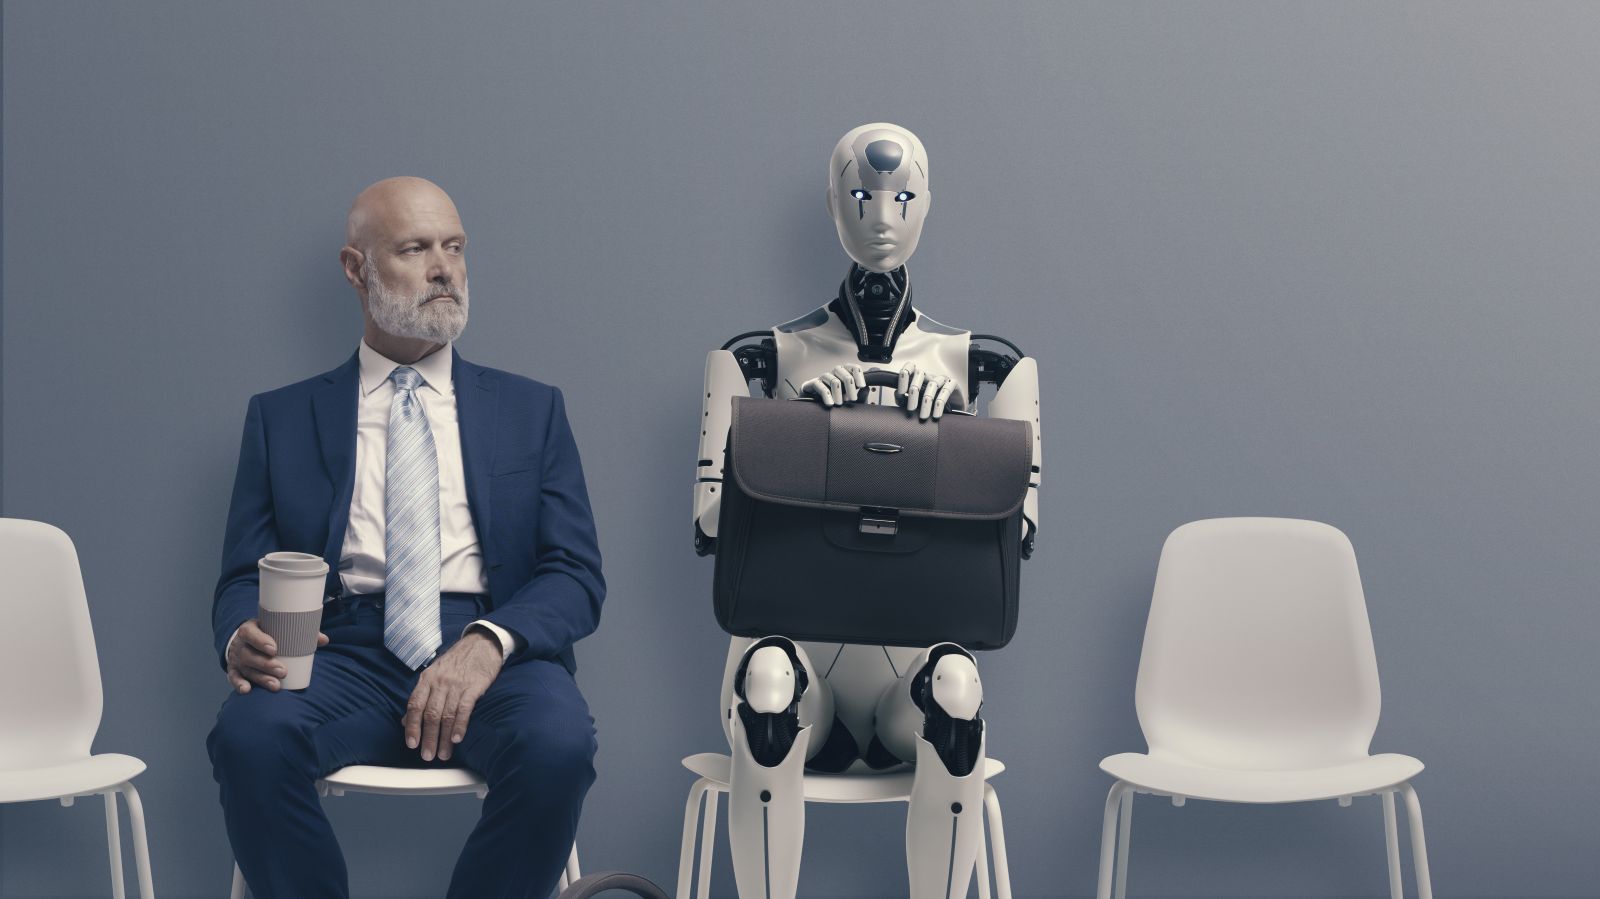
But AI feels different.
AI isn't another piece of software
It is tempting to think of AI as the next efficiency tool.
Learn a few prompts. Automate some emails. Speed up research. Produce a first draft faster. Get the team using it and move on.
I don't think it will be that simple.
AI is beginning to change not only how accounting work is produced, but potentially what work people do, how firms are staffed, how knowledge is captured, how advice is delivered and where clients perceive value.
For a practice owner, that creates an entirely different management challenge.
Which AI systems should the firm use?
What client information can safely be put into them?
Where is the data going?
Who checks the output?
What happens when AI produces something that is plausible, beautifully written — and wrong?
How do you establish governance around staff use?
How do you protect confidential information?
Which existing processes should be automated, and which shouldn't?
And perhaps the biggest question of all: what does my firm need to look like five years from now?
That isn't simply a software implementation.
It requires another substantial investment of attention.
The investment nobody puts on the balance sheet
This is the part of succession planning I think we sometimes miss.
When people talk about whether an owner should continue for another five or ten years, the conversation tends to revolve around money.
Is the practice still profitable?
Can it continue growing?
What is it worth today compared with what it might be worth later?
All perfectly reasonable questions.
But there is another scarce resource involved: mental bandwidth.
Learning an entirely new operating environment takes curiosity, attention and energy.
It means reading. Experimenting. Making mistakes. Training people. Revisiting systems. Working out what is real and what is hype. Establishing controls. Changing processes that may have worked perfectly well for years.
And doing all of that while continuing to run the practice.
For some owners, that will be genuinely exciting.
They will look at AI and see the most interesting period the profession has experienced in decades. They will want to rebuild workflows, develop new services and see where the technology takes them.
If that's you, terrific.
But I don't think every 55-, 60- or 65-year-old practice owner necessarily has to feel the same way.
You are allowed to decide you've done enough laps
There is an odd assumption in business that continuing is somehow the default decision.
Perhaps it shouldn't be.
If you have spent 30 or 40 years building a good accounting practice, looking after clients, employing people and navigating every change the profession has thrown at you, deciding that you don't particularly want to lead the firm through its next technological transformation isn't failure.
It is a commercial and personal decision.
You may decide you want to keep going.
You may decide you would happily remain involved with clients, but would rather somebody else take responsibility for technology, compliance, people and the strategic direction of the firm.
You may want to bring in a younger equity partner.
You may want to merge with a larger organisation that already has the resources and infrastructure required for the next stage.
Or you may decide that, after decades in the profession, this is simply a good time to realise the value you have created and move on to whatever comes next.
None of those decisions is inherently right or wrong.
The mistake is allowing another three or four years to pass without consciously making one.
If 2027 is in your thinking, the conversation belongs in 2026
A well-managed succession rarely starts when somebody finally decides they have had enough.
The best outcomes usually require time.
Time to understand what the practice is worth.
Time to identify the right buyer, merger partner or future equity partner.
Time to improve areas that affect value.
Time to think about staff and clients.
And, importantly, time to structure a transition that works for the owner rather than having circumstances dictate it.
So perhaps the question for established practice owners isn't simply:
“Am I ready to retire?”
That question can feel unnecessarily final.
A better question might be:
“Do I want to be the person responsible for taking this practice through its next five years?”
If the answer is an enthusiastic yes, there is an extraordinary period ahead.
If the answer is “I'm not sure”, that is probably worth exploring.
And if the answer is no, there is nothing particularly alarming about that either.
From handwritten journals and T-accounts to cloud accounting and artificial intelligence, it has already been quite a journey.
You don't automatically have to sign up for the next lap.
If succession, a partial sell-down, merger or bringing in a new equity partner is somewhere in your thinking for 2027, now is the sensible time to start a confidential conversation.